
Marvell Technology (MRVL +3.32%) has emerged as a key player in the artificial intelligence (AI) hardware ecosystem, and that explains why shares of this semiconductor company have jumped by an incredible 189% over the past year.
Marvell designs custom AI chips, networking and optical connectivity components, and storage controllers. The company sees incredible demand for these products over the next five years. We will closely examine Marvell’s key catalysts in this article and find out how much upside investors can expect from this semiconductor stock by 2030.
Image source: The Motley Fool.
Marvell Technology’s revenue and earnings growth are poised to accelerate impressively
Marvell’s revenue in the first six months of fiscal 2027 (which ended on Aug. 1) jumped 32% year over year to $5.16 billion. However, the company sees a significant improvement in its growth rate by the end of the decade.
MRVL Marvell Technology
$251.65+$8.08 (+3.32%)
NASDAQ · As of 4:00 PM ET 10/28/26
Marvell recently noted during its Investor Day presentation that its revenue will increase at a compound annual growth rate (CAGR) of 55% to 60% between fiscal 2026 and fiscal 2031. This outstanding growth will be fueled by solid growth in the company’s AI-related products. Revenue from custom AI chips, for instance, is anticipated to grow at an 80% CAGR through fiscal 2031. Meanwhile, interconnect revenue could increase by a 65% CAGR over the same period.
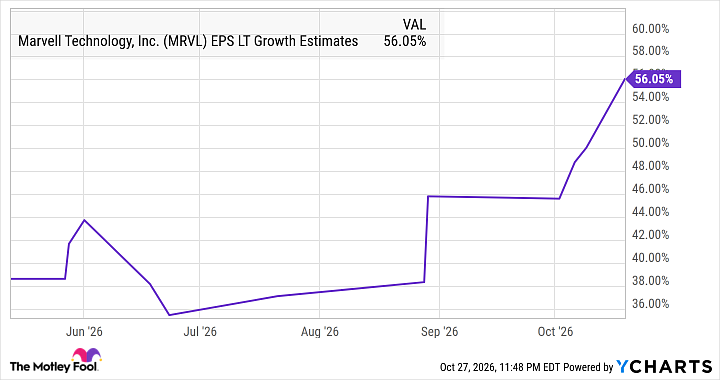
Importantly, Marvell expects that its earnings per share (EPS) growth will exceed its revenue CAGR during this period. That’s because Marvell anticipates its operating expenses to increase at approximately half the rate of its revenue growth. This explains why analysts have substantially increased their long-term EPS growth estimates.
Data by YCharts
Marvell stock can easily double by 2030
Marvell’s adjusted EPS in fiscal 2026 (which ended on Jan. 31, 2026) was $2.84. The company’s revenue growth estimate for the next five fiscal years indicates that its EPS could increase at a CAGR of more than 55%.
Even analysts are expecting its long-term EPS to grow at an annual rate of 56%. Assuming Marvell’s earnings indeed increase at a 56% CAGR through fiscal 2031 (which will end in Jan. 2031), its EPS could reach $26.24 by the end of the decade.
If Marvell trades at 21 times earnings at that time, in line with the tech-focused Nasdaq-100 index’s forward earnings multiple, its stock price could jump to $551 in 2030. That’s 125% higher than Marvell’s current stock price. However, Marvell’s strong growth prospects suggest that it should ideally trade at a premium to the broader index.
That’s why I won’t be surprised to see Marvell stock jumping by a bigger margin by 2030, which is why investors looking to buy the next big semiconductor play should consider buying it before it surges higher.