
A six-figure car sale can register as zero earnings for Social Security purposes, or it can trigger enough withholding to wipe out your checks for the rest of the year. The difference comes down to one question most sellers never…
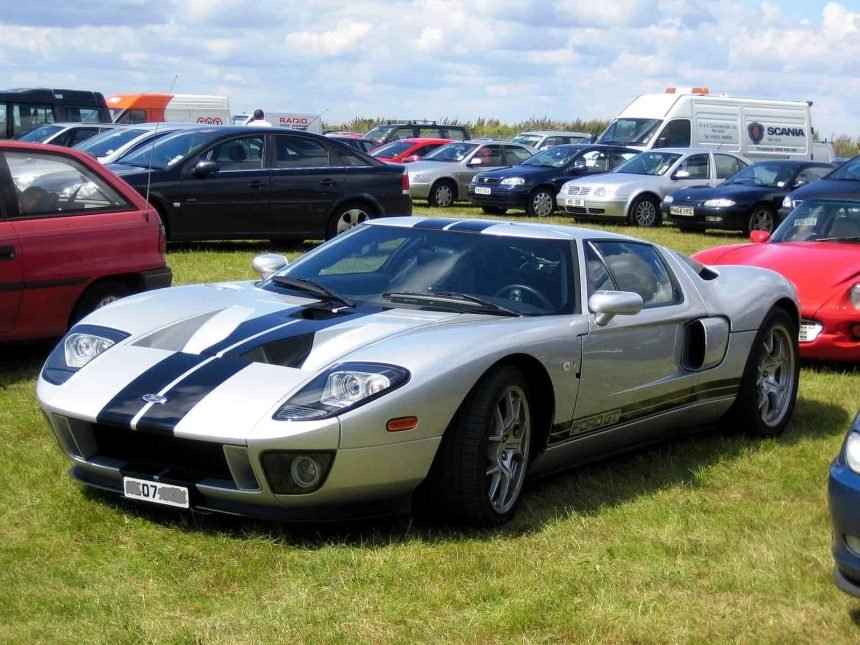
A Barrett-Jackson auction just sold nearly $36 million of collectible vehicles and memorabilia in Las Vegas. The top sale was a 2019 Ford GT Lightweight Carbon Series at $968,000, a supercar from Ford Motor (NYSE:F | F Price Prediction). Sales like that make plenty of longtime owners wonder what their own garage is worth.
A 64-year-old collecting Social Security decides to sell a valuable car he has owned for years. Since he is below the age for full benefits, his checks fall under the earnings test. In 2026, Social Security holds back $1 in benefits for every $2 you earn above $24,480. Does the auction money count as earnings?
The answer depends on why he owned the car.
How a $200,000 Gain Can Count as $0 in Earnings
Under IRS guidance, property held for personal use or as an investment is a capital asset. When Social Security calculates self-employment earnings, it leaves out gains from selling capital assets.
Let’s say he sells the car for $300,000. His adjusted basis is $90,000 and qualifying selling expenses total $10,000, leaving a $200,000 gain. For the earnings test, that gain generally counts as $0, so the sale itself does not trigger benefit withholding.
Why a Dealer With the Same Profit Gets a Very Different Result
Property held mainly to sell to customers in the regular course of business is not a capital asset. If he regularly buys collectible cars to flip them, the cars are inventory and the profit is business income.
| Treatment | Collector | Dealer |
|---|---|---|
| Profit on the sale | $200,000 capital gain | $200,000 net business profit |
| Amount counted for the earnings test | Generally $0 | About $184,700 after the 92.35% adjustment |
Apply the $1-for-$2 rule to the dealer’s figure and Social Security would hold back about $80,110. That tops most people’s annual benefit, so his checks could stop for the rest of the year. At full retirement age, Social Security recalculates his monthly benefit to credit the months benefits were withheld, but he goes without that income in the meantime (we mapped this snare and eight others like it in a free retiree tax trap guide).
His Buying and Selling Habits Decide Whether He Is a Collector or a Dealer
His behavior decides whether he counts as a dealer, including:
- How often he buys and sells. Selling one car after a decade of ownership is different from a regular stream of purchases and sales each year.
- Why he bought each car. Buying to enjoy or hold as it gains value points toward collector status. Buying to resell quickly points toward inventory.
- Whether he advertises. Marketing cars, running listings, or building a customer base looks like a business.
- Whether he operates like a merchant. Fixing up cars for resale, keeping a lot, or working through dealer channels count against him.
- How his tax returns report the cars. His tax reporting should match how he actually held and sold the cars each year.
Personal-Use Cars Follow a One-Sided Tax Rule
The IRS applies its own, uneven rules to gains and losses on personal-use cars. A gain on a personal-use car is taxable. If he sells for less than his basis, a loss on personal-use property such as a car generally is not deductible. Cars held as investments can be treated differently, so records should match intent.
The Gain Can Still Raise Taxes on His Benefits
A capital gain stays out of the earnings test but counts toward adjusted gross income (AGI). That raises his “combined income,” which decides how much of his Social Security is taxable. Once combined income passes $34,000 (single) or $44,000 (joint filing), up to 85% of benefits can be taxed. A $200,000 gain would put him well above the second combined-income threshold, although the exact taxable amount still depends on his benefits and other income.
What to Pin Down Before the Auction
Before consigning the car, he should answer a few questions. Why did he buy it: for enjoyment, as an investment, or to resell? What is his basis and which selling costs reduce the gain? If business activity is involved, where would that income put him compared with the $24,480 limit?
A $968,000 auction result looks like one kind of money, but Social Security can see it two ways. A tax professional can clear up the treatment before the sale and prevent an expensive surprise.
Contact [email protected] for any questions or corrections.