
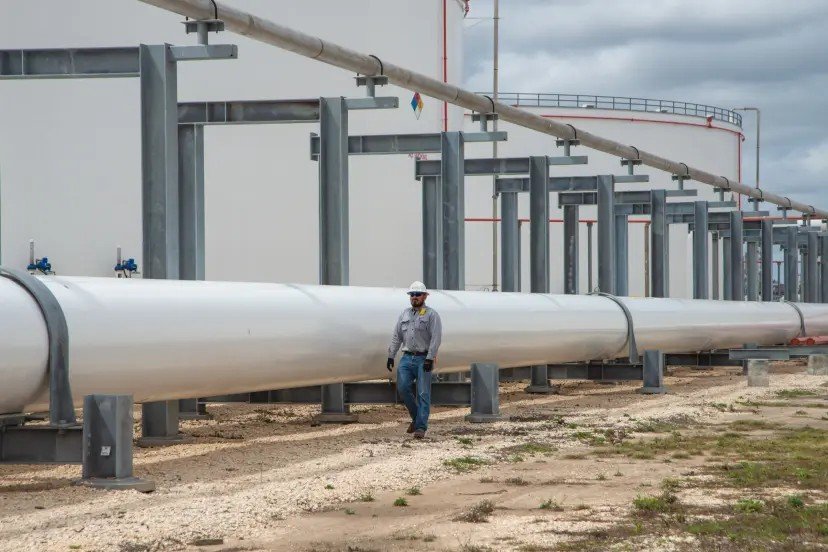
Traffic is rising on the crude oil highway from the Permian Basin to the U.S. Gulf Coast. But the market does not yet see a problem.
“The market may not be pricing a Permian egress problem today. But the physical infrastructure is increasingly pointing toward one,” East Daley Analytics reports.
The Permian still has room to grow crude oil takeaway without another greenfield pipeline, but the candidates for a brownfield project are shrinking, analysts at East Daley wrote.
“Brownfield expansions on Cactus III and Gray Oak could provide the next increments of physical relief, while a sharper increase in crude supply could pressure basis sooner,” the analysts wrote. “Both Cactus III and Gray Oak serve Corpus Christi, so if Houston-bound pipes continue to fill, the market could eventually require a new greenfield crude line to Houston.”
The last major wave of Permian pipeline construction created enough takeaway capacity to keep Midland differentials contained for years, according to East Daley analysts. That cushion is disappearing, the analysts caution. Corpus Christi is already tight, Houston is moving toward similar utilization levels, and the alternative route through Cushing is both more expensive and increasingly constrained.
What stands out to East Daley Analytics is how muted the WTI Midland-to-Houston differential remains despite high utilization on pipelines moving Permian crude toward Gulf Coast export markets. The last time the Permian-to-Houston corridor approached 95% utilization was in September 2018, and the Midland discount widened by more than $8 a barrel. In East Daley’s latest forecast, Houston-bound pipelines will reach 93% utilization by December 2027, while the Midland-to-Houston differential remains below 70 cents in futures trading.
Permian Basin barrels can also move south to Corpus Christi or north to the Cushing hub. East Daley estimates that the Permian-to-Corpus corridor is already 94% utilized. The strong demand reflects Corpus Christi’s position as a preferred export market because of its ability to load very large crude carriers. Even after Plains All American’s expansion of its Cactus III line, only 177,000 barrels a day of remaining capacity is available on that route, East Daley analysts estimate.
The Permian-to-Cushing corridor is only about 52% utilized. If Houston and Corpus fill, producers and marketers can simply send the incremental barrel north. But those barrels have to move north to Cushing, then back south to the Gulf Coast, at a cost of about $4.39 per barrel. Permian barrels also have to compete with barrels moving into Cushing, including potentially more Canadian crude.
“Put differently, spare pipeline capacity is not the same thing as cheap, economically equivalent takeaway capacity. East Daley estimates that only about 500,000 barrels a day of capacity remains on the more direct routes from the Permian toward Gulf Coast markets. Continued Permian production growth will steadily consume that remaining headroom,” the analysts wrote.